Michael Ioane
Article IV
Summary Guide Article
Guide: Taxpayer Rights and Protections
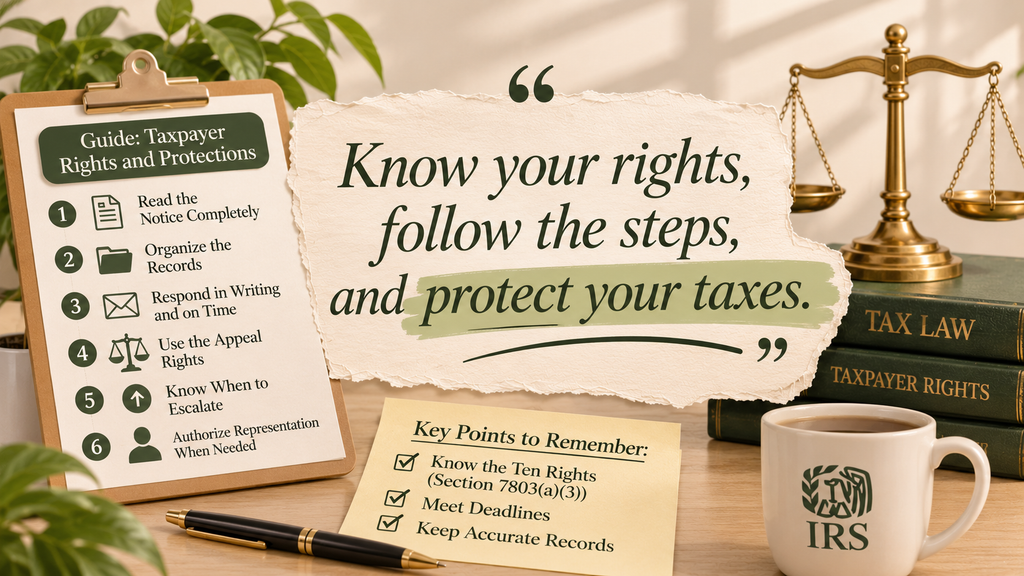
This guide condenses the main points on taxpayer rights into a working sequence. It is written for general education and reflects federal law as I understand it. Specific situations require reviewing the notice you received and the facts involved.
Step One: Read the Notice Completely
Every IRS notice states what the IRS proposes, the tax period involved, and a response date. Identify the notice number and the deadline first. Many rights, including the right to petition the Tax Court and to request a Collection Due Process hearing, expire on a fixed date that cannot be extended by the IRS.
Step Two: Organize the Records
Collect returns, statements, receipts, and correspondence for the period in question. Keep a log of every call and letter with dates and names. Send documents by a trackable method and keep copies.
Step Three: Respond in Writing and on Time
Address each item the IRS raised. If more time is needed, ask for it in writing before the response date passes. If you disagree, state the disagreement and attach support.
Step Four: Use the Appeal Rights
If the IRS does not agree, request a conference with the IRS Independent Office of Appeals when the notice offers it. Appeals consider the hazards of litigation and can settle cases. If a notice of deficiency is issued, calendar the 90-day petition deadline immediately.
Step Five: Know When to Escalate
If a problem causes financial hardship or has not been resolved through normal channels, the Taxpayer Advocate Service can be requested through Form 911. If you face a levy, review the Collection Due Process options. If joint filing creates a problem, review Section 6015 relief.
Step Six: Authorize Representation When Needed
Use Form 2848 to authorize an attorney, certified public accountant, or enrolled agent to act for you. Representation is especially valuable when an examination is under way, a large balance is at issue, or the facts are complex.
Key Points to Remember
The ten rights in Section 7803(a)(3) frame your dealings with the IRS. Other sections of the Code provide the specific protections and tie them to deadlines. Accurate records, timely written responses, and informed use of appeal rights are the practical foundation of every taxpayer’s legal protection.
This article is provided for general educational purposes and reflects the author’s understanding of the law at the time of writing. It is not legal, tax, or financial advice, and it does not create a professional relationship. Laws change and individual circumstances differ, so consult a licensed professional about your specific situation.
Continue Learning with Michael Ioane
Build your understanding of asset protection and business planning with the Asset Protection Manual . Explore taxation and private trust planning in Boston Tea Party . Both books are available on Amazon.